Want to get smarter about taxes?
The Tax Pible has tax tips, guides, video tutorials, and expert insights. Stay up to date with the latest tax news and watch the UKs first tax podcast - the Piecast
File your Self Assessment - For FREE
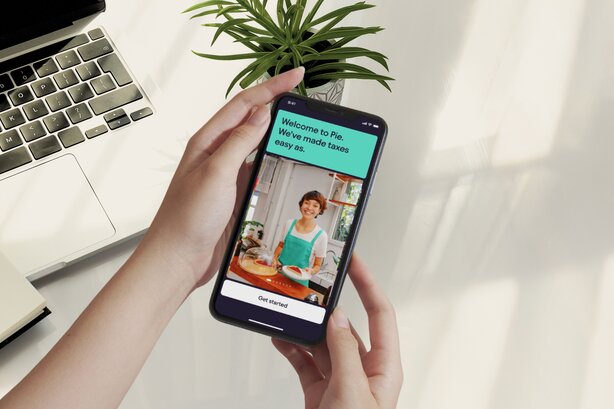
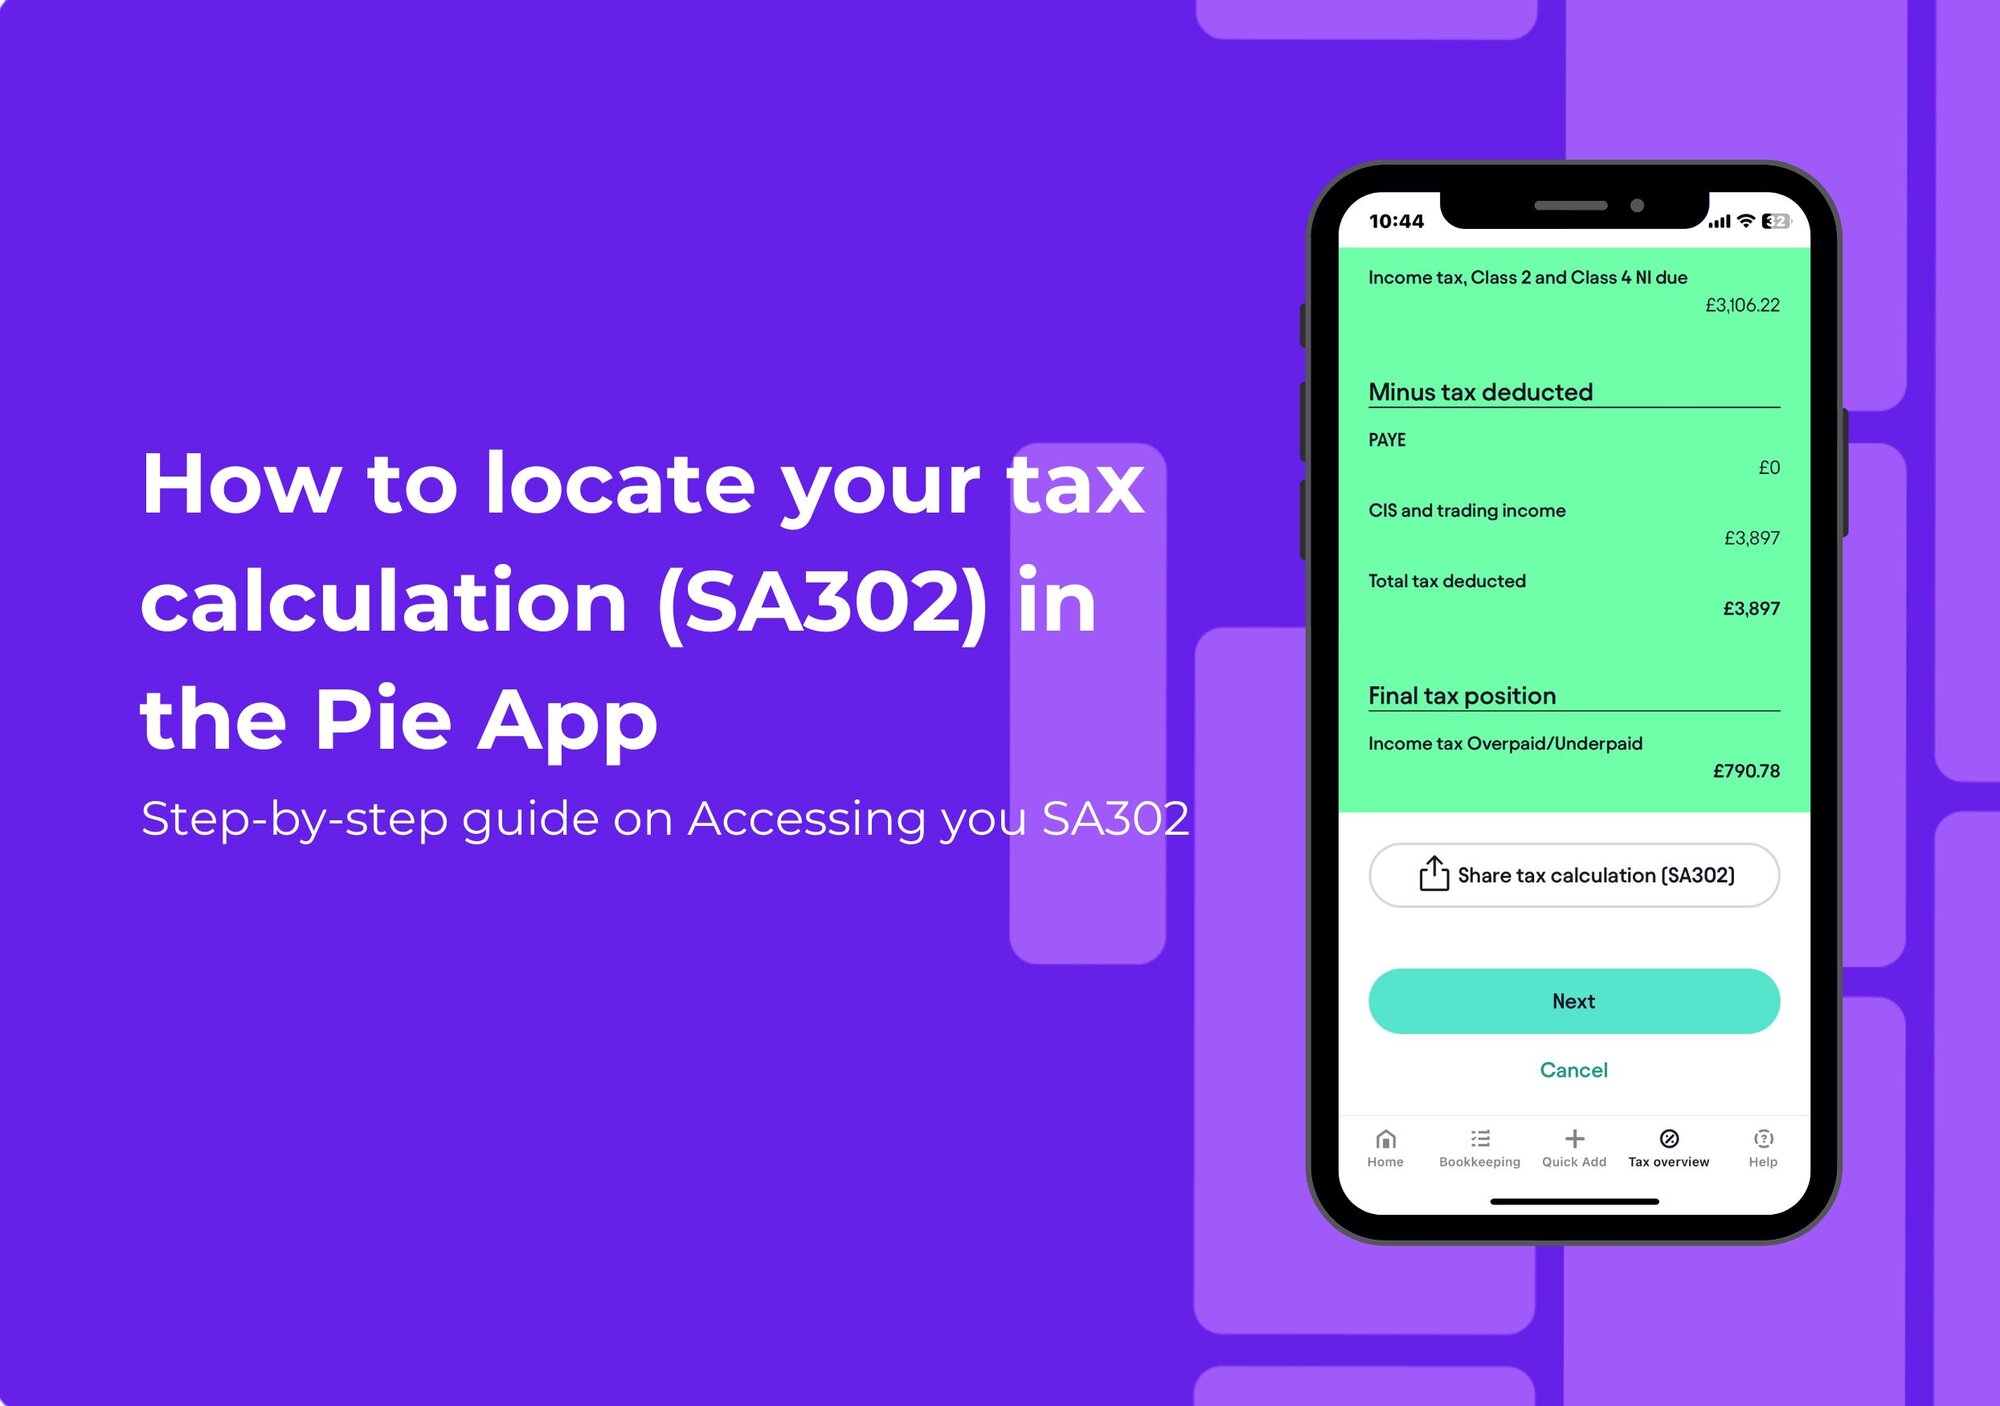
Manage your self-assessment in one, easy to use App
Save money, time and effort with Pie
Add multiple incomes and view your tax in ‘Real Time’
File directly to HMRC - for FREE
The Free Self Assessment App.




Want regular updates from us?
Sign up for regular tax tips and news sent straight to your inbox.